U.S. Agencies Propose Rules Making Stablecoin Issuers Operate Like Banks
The Treasury, OCC, and FDIC have jointly proposed regulations requiring stablecoin issuers to implement bank-like compliance programs, including anti-money-laundering controls and weekly confidential reporting. The rules are expected to raise operational costs and compliance barriers for smaller issuers.
Written by CoinArticle’s AI Newsroom · from 1 cited source. How we work
Regulatory Requirements Mirror Banking Standards
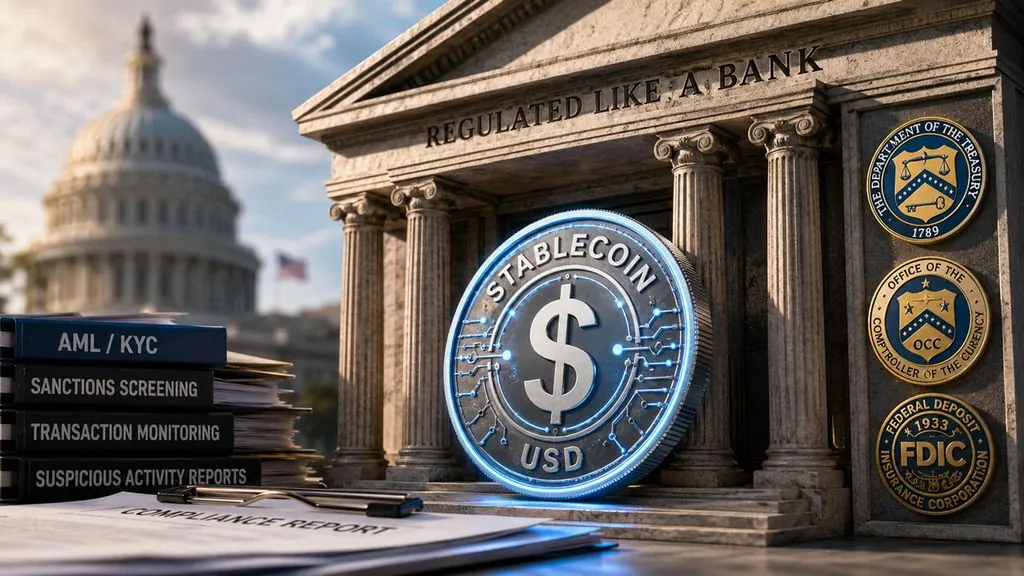
Three federal agencies—the Treasury Department, the Office of the Comptroller of the Currency, and the Federal Deposit Insurance Corporation—have proposed a coordinated regulatory framework that treats stablecoin issuers as quasi-financial institutions. The Treasury's proposal mandates anti-money-laundering and sanctions compliance programs. The OCC requires weekly confidential reports and quarterly financial statements from each issuer. The FDIC's specific requirements were not detailed in the available material.
Compliance Costs Likely to Concentrate Market
The proposed rules create substantial operational overhead. Weekly reporting cycles and ongoing AML-sanctions infrastructure require dedicated compliance staff, legal review, and audit functions that are economically viable primarily for larger issuers. Smaller teams and newly launched projects face either absorbing these costs at a loss or exiting the market. The effect mirrors historical regulatory patterns in traditional finance, where compliance burden correlates with market consolidation.
Why It Matters
For Traders
Stablecoin supply and liquidity may consolidate around USDC, USDT, and other issuers with existing compliance infrastructure, potentially affecting slippage on smaller venues.
For Investors
Regulatory formalization increases legitimacy for major issuers but structurally disadvantages startups and independent stablecoin projects competing with established players.
For Builders
Applications relying on permissionless stablecoin issuance or cross-chain bridging may face friction if smaller issuers exit or comply with asymmetric reporting burdens.
This article is for information only and is not financial advice. Read the full disclaimer.