Strategy's Q1 Loss, Dilution and MSCI Exit Put Pressure on MSTR Shareholders
Strategy, the largest corporate Bitcoin holder, reported a $12.54 billion net loss in Q1 2026 driven by an unrealized Bitcoin mark-to-market loss, while sources differ on the timing and scale of later share issuance and index changes. Sources also disagree on whether MSCI's removal of Strategy from its global indexes is already confirmed and how Bitcoin's price level compares across reporting windows.
Written by CoinArticle’s AI Newsroom · from 2 cited sources. How we work
Reported Q1 Loss and Bitcoin Position
Strategy posted a net loss of $12.54 billion for the first quarter of 2026, according to CryptoPotato's summary of the company's results, with a $14.46 billion unrealized loss on its Bitcoin holdings accounting for most of the shortfall. Loss attributable to common stockholders was $12.77 billion, or $38.25 per diluted share, compared with $4.23 billion a year earlier. Excluding Bitcoin accounting, the company's software business reported revenue of $124.3 million, up 11.9% year over year, and gross profit of $83.4 million.
On the holdings side, the company bought 89,599 BTC during the quarter, bringing its total to 818,334 BTC, a 22% year-to-date increase per the same report. Crypto Briefing's later coverage puts the stack at 850,849 BTC as of mid-November 2026, up 26% year to date, which is consistent with continued accumulation after the quarter closed.
Share Count, Dilution and Capital Allocation
The sources describe the company's equity issuance differently in scope. CryptoPotato reports $7.37 billion raised through its at-the-market program in Q1 alone and close to $12 billion across 2026 to date. Crypto Briefing reports a narrower recent event: about 2.09 million common shares sold in the week of November 9 to 15, raising $244.7 million. Those figures are not contradictory, since they cover different periods, but they should not be read as the same program.
Crypto Briefing states that 84% of that week's proceeds, or $206.3 million, went to repurchasing preferred shares, with only $33.4 million used for Bitcoin. It also reports the common share count rising from roughly 287 million at the end of 2025 to about 422 million by late September 2026, and that diluted Bitcoin per share is down 3.7% year to date. CryptoPotato, by contrast, focuses on the preferred stock side, describing STRC as having reached $8.5 billion in notional value and cumulative dividends above $693 million across 23 distributions, according to CFO Andrew Kang.
On the call cited by CryptoPotato, Executive Chairman Michael Saylor said the company would "probably sell some Bitcoin to pay a dividend just to inoculate the market." Analyst Jeff Park flagged that comment as more significant than prior statements on the subject. The sources report this as a stated possibility, not an executed sale.
Market Reaction and Index Removal
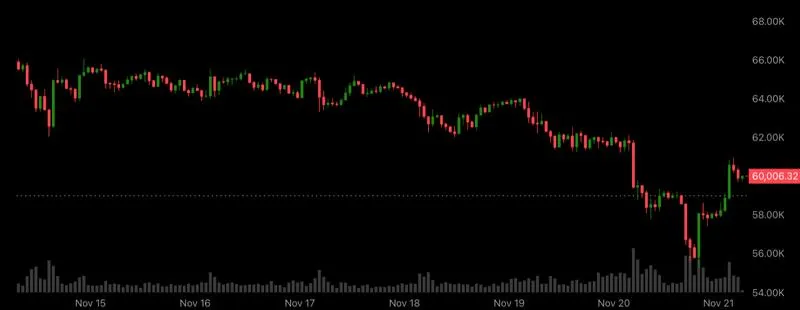
CryptoPotato reports MSTR closing near $187 and falling roughly 3.5% in after-hours trading after the earnings release, with Bitcoin around $81,000 at the time of writing. Crypto Briefing reports the stock closing near $96.50, below an average issuance price of about $117, with Bitcoin below $65,000. The two price levels reflect different dates and cannot be reconciled from the sources alone, and readers should treat each as a snapshot of its own reporting window.
Crypto Briefing states that MSCI has announced Strategy will be removed from its global indexes after November 30, 2026, and that MSCI appears to view the company as a vehicle for holding Bitcoin rather than an operating business. CryptoPotato does not mention an index removal. Passive-fund selling tied to such a change is a documented mechanism, but the sources do not quantify its likely size.
Cost Basis and Obligations
Crypto Briefing puts the company's average cost basis at about $75,452 per Bitcoin, which would leave the holdings underwater if Bitcoin trades below that level, as the source states it did at the time of writing. It also cites annual preferred and debt obligations of approximately $1.56 billion. Those figures come from a single source and were not corroborated by CryptoPotato, so they should be read as that outlet's reported numbers.
Peter Schiff's criticism, referenced in both pieces, argues that dividends are funded by continuous issuance of new shares. Strategy has rejected that characterization, pointing to its Bitcoin holdings as a balance sheet backstop.
Why It Matters
For Traders
Conflicting reported prices and an MSCI removal date of November 30 make near-term MSTR volatility and possible passive-fund selling key variables to monitor.
For Investors
Rising share count and preferred obligations relative to Bitcoin holdings shift risk toward common equity holders, a structural point that persists regardless of short-term price moves.
For Builders
Treasury strategies that fund Bitcoin accumulation through equity issuance depend on index membership and share price, so protocols tied to this model should stress-test those dependencies.
This article is for information only and is not financial advice. Read the full disclaimer.